Form an LLC for Your Hawaii Insurance Agency
Protect your personal assets from liability claims, maximize tax deductions, and establish a professional business structure for your insurance practice in Hawaii. Year one in Hawaii costs $62.50 in mandatory state charges, then $12.50 a year.
Last updated: June 2026
Formation Services Compared
Ready to form your Hawaii LLC?
Compare the formation services we partner with before you pay: pricing, registered agent renewal costs and BBB ratings side by side.
Affiliate disclosure: We may earn a commission at no extra cost to you.
Start your LLC with ZenBusiness$0 service fee plus your state's filing fee. Registered agent is extra: $99 for the first year when you form with them, then $199/yr.Form your LLC with Northwest ($39 + state fee)Includes a year of registered agent service. That enrolls you by default in annual report filing at $100 plus state fees, charged automatically to your saved payment method and cancellable any time.Not sure which service is right? Compare formation services →
Yes, forming an LLC is worth it for insurance agents in Hawaii due to significant liability protection and tax advantages.
Insurance agents face constant exposure to errors and omissions claims that can exceed standard E&O insurance limits. An LLC provides essential personal asset protection while enabling tax deductions for licensing fees, continuing education, and marketing expenses that are substantial in the insurance industry.
Key Benefits of an LLC for Hawaii
Enhanced liability protection beyond E&O insurance
Shields personal assets from client lawsuits, regulatory fines, and claims that exceed your errors and omissions insurance coverage limits.
Professional credibility for agency licensing
Creates a formal business entity that enhances credibility with carriers, clients, and regulatory bodies when applying for agency licenses in Hawaii.
Tax deductions for insurance-specific expenses
Deduct E&O insurance premiums, continuing education costs, licensing fees, lead generation tools, and CRM software as business expenses.
Simplified business banking and contracts
Open business accounts more easily and sign carrier contracts under your LLC name, improving financial organization and professional relationships.
Flexibility for agency growth and partnerships
Easily add partners, employees, or sub-agents to your structure while maintaining clear ownership and profit-sharing arrangements.
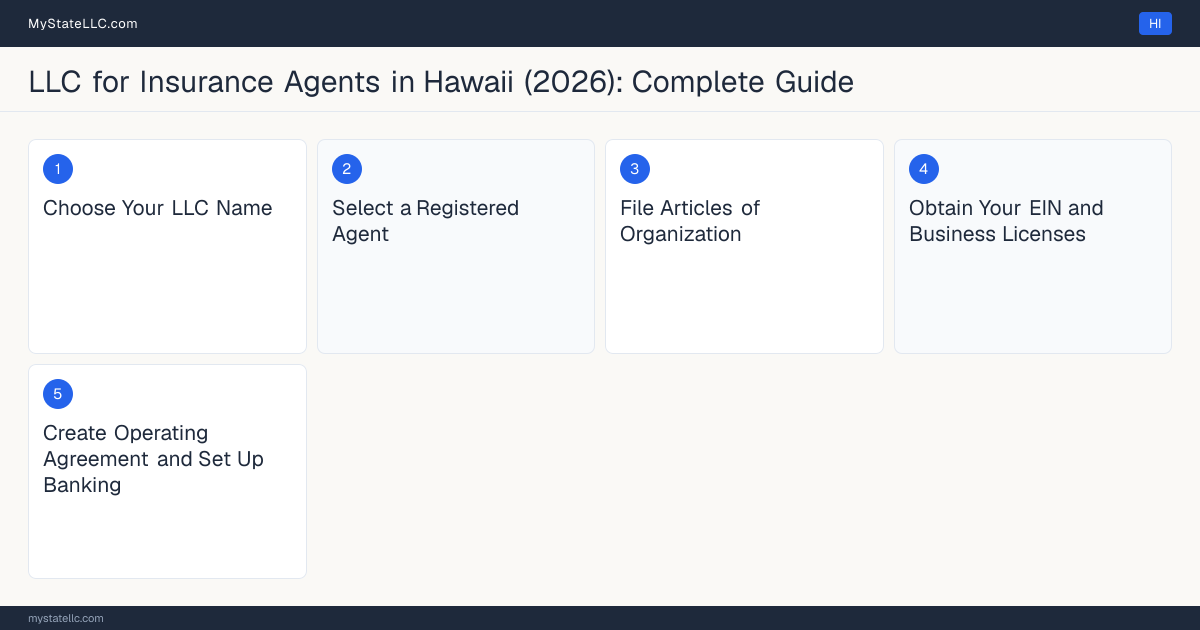
How to Form Your LLC
- 1
Choose Your LLC Name
Select a professional name ending with 'LLC' or 'Limited Liability Company.' Avoid names suggesting you're a direct insurer. Check availability through Hawaii's Department of Commerce and Consumer Affairs and ensure the name works for your agency licensing applications.
- 2
Select a Registered Agent
Choose someone to receive legal documents on behalf of your LLC. Many insurance agents use a professional service to maintain privacy and ensure reliable receipt of important notices, especially if you work from home or travel frequently for client meetings.
- 3
File Articles of Organization
Submit your Articles of Organization online at cca.hawaii.gov with the $50 filing fee. Include your business purpose as 'insurance agency services' or similar language that aligns with your planned insurance licenses.
- 4
Obtain Your EIN and Business Licenses
Get your Federal EIN from the IRS immediately after formation. Then apply for your Hawaii insurance producer license and any required agency licenses, using your LLC's legal name and EIN on all applications.
- 5
Create Operating Agreement and Set Up Banking
Draft an operating agreement outlining profit distributions, especially important if you plan to add partners or sub-agents. Open a business bank account using your EIN to maintain proper separation between personal and business finances for tax purposes.
Tax Considerations
Self Employment Tax
As a single-member LLC, you'll pay self-employment tax on your insurance commissions and fees. However, you can deduct the employer portion of this tax, and legitimate business expenses reduce your taxable income.
Deductions
Insurance agents can deduct E&O insurance premiums, state licensing fees, continuing education courses, CRM software subscriptions, lead generation costs, marketing materials, office expenses, business mileage for client visits, and professional association memberships.
State Taxes
Hawaii LLCs pay an annual report fee of $15 (one of the lowest in the country). Pass-through income is taxed at Hawaii's individual income tax rate (up to 11%), one of the highest in the nation. Hawaii also has a General Excise Tax (GET), a gross receipts tax of 4% (4.5% in Honolulu) on most business revenue, paid quarterly.
Hawaii Licensing Requirements for Insurance Agents
In Hawaii, Insurance Agents are regulated by the Hawaii Insurance Division, Department of Commerce and Consumer Affairs. A Hawaii Insurance Producer License is required to practice legally. An LLC transacting insurance in Hawaii must obtain a Business Entity Producer License from the Hawaii Insurance Division. At least one member or manager must hold an active individual producer license and be designated to supervise the LLC's insurance activities.
Do you need business insurance?
An LLC’s liability shield protects your personal assets from the business’s debts and lawsuits, but it does not protect the business itself, client injuries, property damage, and lawsuits against the company can still put its income and assets at risk.
Business insurance providers for insurance agents
Typical cost for insurance agents: general liability $29/mo median · professional liability $65/mo · limits $1M per occurrence / $2M aggregate (GL, chosen by 89%); $1M per occurrence / $1M aggregate (E&O, chosen by 83%), as of September 2026, per Insureon - Insurance Agent Business Insurance Cost. These are industry-wide medians, not quotes from the providers below. No figure in this paragraph describes a policy offered by any provider below, and the limits shown are the basis of that median rather than terms offered by any of them.
Disclosure: NEXT Insurance (ERGO NEXT), Hiscox and Thimble pay us when you request a quote through our link, whether or not you buy a policy. Embroker does not pay us. This does not affect our editorial comparisons, and coverage details always come from the insurer's own documents.
| Provider | Stated focus | AM Best rating | Insurer’s site |
|---|---|---|---|
| NEXT Insurance (ERGO NEXT) | online small business insurance for the self-employed, freelancers, contractors, sole proprietors, and micro-businesses across 1,300+ professions | A+ | Visit NEXT Insurance (ERGO NEXT) |
| Hiscox | small-business and professional liability (errors & omissions) coverage for professional-services freelancers, consultants, and specialty professions across 180+ occupations | A | Visit Hiscox |
| Embroker | digital commercial insurance (D&O, cyber, tech E&O, EPLI, professional liability) for venture-funded startups, tech companies, law firms, VC/PE firms, and other professional-services businesses | N/A | Visit Embroker |
| Thimble | on-demand, short-term (hourly/daily/monthly) general liability and professional liability insurance for freelancers, gig workers, and small businesses across 129+ industries | N/A | Visit Thimble |
Stated focus reproduces how each insurer describes its own business on its own website. It is not our recommendation, and we do not rank these providers.
IncACA is not an insurance agency, producer, or broker, and is not licensed in any state. We do not sell, solicit, or negotiate insurance, we take no applications, and we do not quote, bind, or place coverage. Every quote is requested on the insurer’s own website. This guide is general information, not insurance, legal, or financial advice. Coverage needs, requirements, and pricing vary by business, location, and carrier underwriting. Confirm policy details directly with a licensed insurance carrier or agent before making a purchasing decision.
This guide is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Read the asset-protection claims on this page narrowly. An LLC separates the company’s own obligations from what you own personally, so a trade creditor, a commercial lease, a business loan without a personal guarantee, or a judgment against the company normally reaches the company rather than your home or savings. It does not put a wall around what you personally do: you remain personally answerable for your own professional negligence, and forming an LLC does not shield a licensed practitioner from a malpractice or negligence claim arising from their own work. Professional liability cover (errors and omissions, or malpractice cover in some trades) is what answers a claim like that, not the entity. You are also personally exposed on anything you sign a personal guarantee for, and on the payroll and sales taxes most states collect from responsible individuals. Whether the shield holds at all turns on facts this page cannot see, including how the company was capitalised, whether its money is kept separate from yours, and what your state’s courts have done with veil-piercing claims. Confirm your own position with an attorney licensed in your state and with the board that licenses your trade, and confirm your cover with a licensed insurance agent, before you rely on anything here.
Frequently Asked Questions
Ready to Form Your Hawaii LLC?
Affiliate disclosure: We may earn a commission at no extra cost to you.
Start your LLC with ZenBusiness$0 service fee plus your state's filing fee. Registered agent is extra: $99 for the first year when you form with them, then $199/yr.Form your LLC with Northwest ($39 + state fee)Includes a year of registered agent service. That enrolls you by default in annual report filing at $100 plus state fees, charged automatically to your saved payment method and cancellable any time.Not sure which service is right? Compare formation services →