Start Your Ohio Landscaping LLC Today
Protect your personal assets from property damage claims while unlocking tax deductions for equipment, vehicles, and materials. Year one in Ohio costs $99 in mandatory state charges.
Last updated: September 2026
Formation Services Compared
Ready to form your Ohio LLC?
Compare the formation services we partner with before you pay: pricing, registered agent renewal costs and BBB ratings side by side.
Affiliate disclosure: We may earn a commission at no extra cost to you.
Start your LLC with ZenBusiness$0 service fee plus your state's filing fee. Registered agent is extra: $99 for the first year when you form with them, then $199/yr.Form your LLC with Northwest ($39 + state fee)Includes a year of registered agent service.Not sure which service is right? Compare formation services →
Yes, forming an LLC is absolutely worth it for landscaping business owners in Ohio.
The liability protection alone justifies the $99 filing fee when you consider potential property damage or injury claims from client sites. Plus, you'll gain professional credibility for commercial contracts and access to valuable tax deductions for your equipment, vehicles, and materials.
Key Benefits of an LLC for Ohio
Protection from Property Damage Claims
Shield your personal assets from lawsuits related to accidental damage to client properties, irrigation system failures, or landscape installation issues.
Commercial Contract Credibility
Many commercial property managers and municipalities require landscaping contractors to be formally incorporated, giving your LLC a competitive advantage in bidding.
Equipment and Vehicle Tax Deductions
Deduct business expenses for mowers, trimmers, trucks, trailers, fuel, and maintenance costs that can significantly reduce your tax burden.
Seasonal Worker Employment Benefits
Hire seasonal employees more easily while protecting yourself from employment-related liability claims during Ohio's busy growing season.
Business Banking and Credit Access
Establish business credit separate from personal credit, making it easier to finance expensive landscaping equipment and expand your operations.
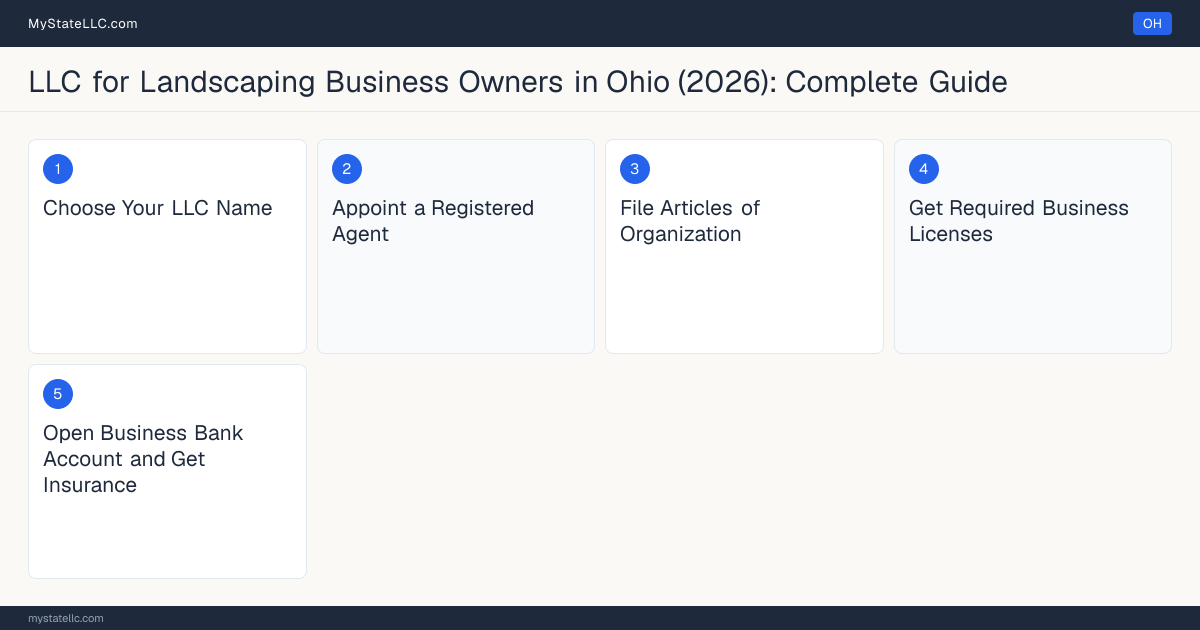
How to Form Your LLC
- 1
Choose Your LLC Name
Select a professional name that includes 'LLC' and reflects your landscaping services. Avoid names too similar to existing Ohio businesses. Consider something like '[Your Name] Landscaping LLC' or '[City] Lawn Care Services LLC' that builds local trust.
- 2
Appoint a Registered Agent
Choose someone available during business hours to receive legal documents. Many landscapers use a professional service to ensure they don't miss important notices while working on job sites.
- 3
File Articles of Organization
Submit your formation documents to the Ohio Secretary of State online at ohiosos.gov with the $99 filing fee. The Ohio Secretary of State publishes no standard processing time for this filing.
- 4
Get Required Business Licenses
Obtain necessary landscaping licenses in Ohio, which may include commercial applicator licenses for pesticides or fertilizers, and check local permit requirements for irrigation work.
- 5
Open Business Bank Account and Get Insurance
Separate business finances with a dedicated account and secure general liability insurance that covers property damage and injuries on client sites, essential for landscaping work.
Tax Considerations
Self Employment Tax
As an LLC owner in Ohio, you'll pay self-employment tax on your landscaping income, but you can reduce this burden through proper business expense deductions and potentially electing S-Corp taxation as your business grows.
Deductions
Landscaping LLCs can deduct mowing equipment, trimmers, blowers, trucks and trailers, fuel costs, plant materials and seeds, fertilizers and chemicals, tool maintenance and repairs, business insurance premiums, and uniform costs, potentially saving thousands annually.
State Taxes
Ohio taxes business income through its individual income tax, but the Business Income Deduction lets you deduct up to $250,000 of business income (for most filers), and business income above that's taxed at a flat 3%. Ohio also imposes the Commercial Activity Tax (CAT), a 0.26% gross receipts tax that applies only to Ohio gross receipts above $6 million, smaller businesses owe no CAT. Ohio LLCs don't file an annual report. Ohio has no annual report requirement for LLCs.
Do Landscaping Business Owners Need a License in Ohio?
Ohio issues no license of its own for this trade, but a related state credential reaches the work. Ohio issues no landscaping contractor license, and the Ohio Construction Industry Licensing Board licenses only heating, ventilating and air conditioning, refrigeration, electrical, plumbing and hydronics contractors under Section 4740.01 of the Revised Code. Section 927.51 puts a landscaper who sells nursery stock as part of a grounds improvement project inside the definition of dealer, and Section 927.53 makes each dealer pay the Director of Agriculture an annual license fee of $125 for every place of business, with no value floor and no exemption for small jobs. Person is defined to include a corporation or company, so the business holds the license.
Do you need business insurance?
An LLC’s liability shield protects your personal assets from the business’s debts and lawsuits, but it does not protect the business itself, client injuries, property damage, and lawsuits against the company can still put its income and assets at risk.
Business insurance providers for landscaping business owners
Typical cost for landscaping business owners: general liability $51/mo median · limits $1M per occurrence / $2M aggregate (GL, chosen by 94%), as of September 2026, per Insureon - Landscaping Business Insurance Cost. These are industry-wide medians, not quotes from the providers below. No figure in this paragraph describes a policy offered by any provider below, and the limits shown are the basis of that median rather than terms offered by any of them.
Disclosure: NEXT Insurance (ERGO NEXT), Hiscox and Thimble pay us when you request a quote through our link, whether or not you buy a policy. Embroker does not pay us. This does not affect our editorial comparisons, and coverage details always come from the insurer's own documents.
| Provider | Stated focus | AM Best rating | Insurer’s site |
|---|---|---|---|
| NEXT Insurance (ERGO NEXT) | online small business insurance for the self-employed, freelancers, contractors, sole proprietors, and micro-businesses across 1,300+ professions | A+ | Visit NEXT Insurance (ERGO NEXT) |
| Hiscox | small-business and professional liability (errors & omissions) coverage for professional-services freelancers, consultants, and specialty professions across 180+ occupations | A | Visit Hiscox |
| Embroker | digital commercial insurance (D&O, cyber, tech E&O, EPLI, professional liability) for venture-funded startups, tech companies, law firms, VC/PE firms, and other professional-services businesses | N/A | Visit Embroker |
| Thimble | on-demand, short-term (hourly/daily/monthly) general liability and professional liability insurance for freelancers, gig workers, and small businesses across 129+ industries | N/A | Visit Thimble |
Stated focus reproduces how each insurer describes its own business on its own website. It is not our recommendation, and we do not rank these providers.
IncACA is not an insurance agency, producer, or broker, and is not licensed in any state. We do not sell, solicit, or negotiate insurance, we take no applications, and we do not quote, bind, or place coverage. Every quote is requested on the insurer’s own website. This guide is general information, not insurance, legal, or financial advice. Coverage needs, requirements, and pricing vary by business, location, and carrier underwriting. Confirm policy details directly with a licensed insurance carrier or agent before making a purchasing decision.
This guide is general information, not legal or tax advice, and reading it does not create an attorney-client relationship. Read the asset-protection claims on this page narrowly. An LLC separates the company’s own obligations from what you own personally, so a trade creditor, a commercial lease, a business loan without a personal guarantee, or a judgment against the company normally reaches the company rather than your home or savings. It does not put a wall around what you personally do: you remain personally answerable for your own professional negligence, and forming an LLC does not shield a licensed practitioner from a malpractice or negligence claim arising from their own work. Professional liability cover (errors and omissions, or malpractice cover in some trades) is what answers a claim like that, not the entity. You are also personally exposed on anything you sign a personal guarantee for, and on the payroll and sales taxes most states collect from responsible individuals. Whether the shield holds at all turns on facts this page cannot see, including how the company was capitalised, whether its money is kept separate from yours, and what your state’s courts have done with veil-piercing claims. Confirm your own position with an attorney licensed in your state and with the board that licenses your trade, and confirm your cover with a licensed insurance agent, before you rely on anything here.
Frequently Asked Questions
Ready to Form Your Ohio LLC?
Affiliate disclosure: We may earn a commission at no extra cost to you.
Start your LLC with ZenBusiness$0 service fee plus your state's filing fee. Registered agent is extra: $99 for the first year when you form with them, then $199/yr.Form your LLC with Northwest ($39 + state fee)Includes a year of registered agent service.Not sure which service is right? Compare formation services →